When Pilates Studios Need Umbrella Insurance in 2026
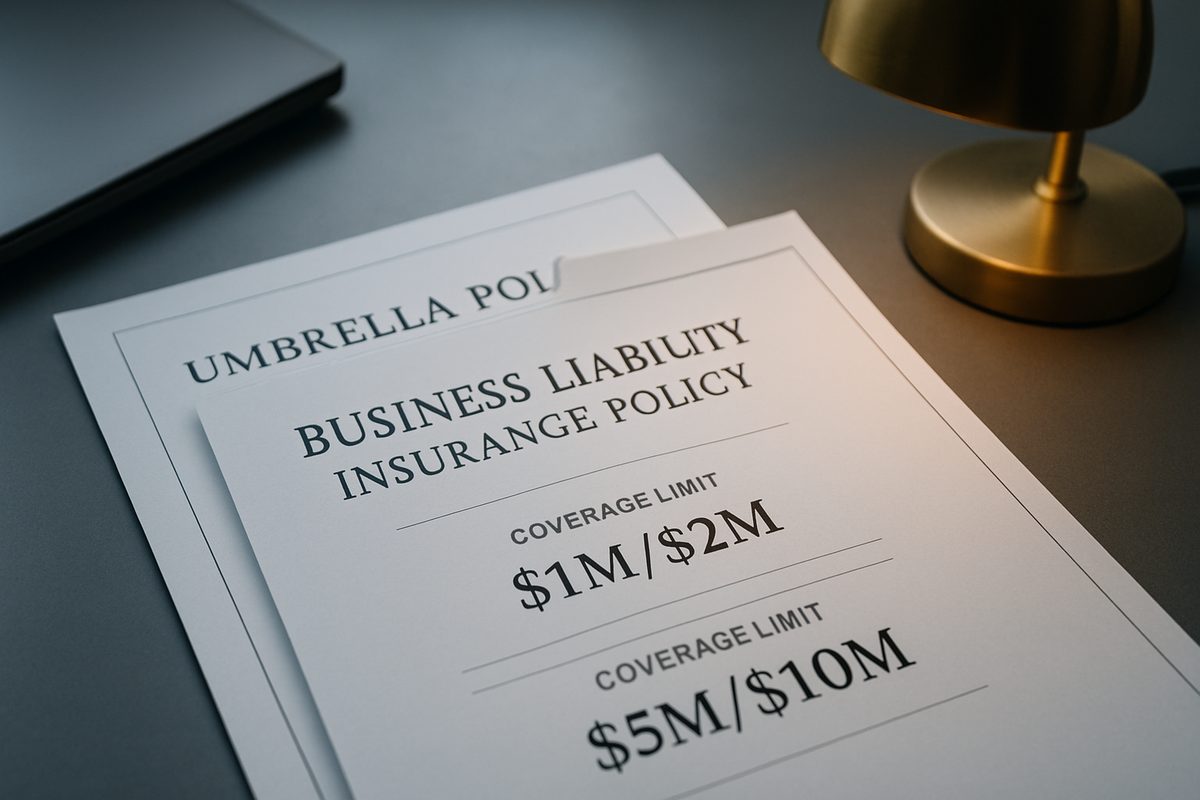
Average injury settlements now exceed $1.2 million while standard studio limits remain at $1M/$2M. Here's when umbrella coverage becomes essential.
Key Takeaways
- Average personal injury settlements now exceed $1.2 million, while standard Pilates studio liability limits remain at $1 million per occurrence and $2 million aggregate, creating a growing coverage gap in 2026.
- Commercial umbrella insurance adds $1 million to $5 million in excess liability coverage for $30 to $75 per month, protecting studio owners when premises liability or bodily injury claims exceed primary policy limits.
- Umbrella policies almost never cover professional liability claims, meaning they protect against reformer falls and premises injuries but not instruction-related negligence lawsuits.
- Multi-location studios, high-volume operations, and businesses in California, New York, and Florida face the highest exposure and should prioritize umbrella coverage during policy renewals.
- Injury claims in Pilates average $25,000, but catastrophic injuries involving spinal damage or traumatic brain injury can produce settlements and legal costs that easily exceed $1 million.
Why Standard Coverage Limits No Longer Match 2026 Claim Reality
The industry-standard liability limits for boutique fitness studios have remained static at $1 million per occurrence and $2 million aggregate even as personal injury settlements have climbed significantly. The average personal injury settlement now exceeds $1.2 million, and in major metropolitan areas that figure rises above $2 million.
For Pilates studios, the exposure is real. Injury claims in Pilates average $25,000, with common scenarios including clients falling from reformer carriages during standing exercises. While most claims settle within primary policy limits, serious injuries involving spinal damage, fractures, or traumatic brain injury can produce settlements and legal defense costs that easily exceed $1 million.
Even when a studio ultimately prevails in court, legal defense costs can run into five-figure amounts. A single catastrophic claim that exhausts a $1 million general liability limit leaves the studio owner personally liable for the excess, along with ongoing legal fees.
What Umbrella Insurance Actually Covers for Pilates Studios
Commercial umbrella insurance protects studio owners from paying out-of-pocket for any legal fees and awarded damages that exceed their primary policy. The coverage kicks in after a claim exceeds limits on general liability insurance, employer's liability insurance, commercial auto insurance, and hired and non-owned auto insurance.
Umbrella policies typically add coverage in increments of $1 million to $5 million, sitting on top of existing policies as a safety net. If a client suffers a reformer-related fall that results in permanent spinal injury and a jury awards $2.5 million, the primary general liability policy pays the first $1 million and the umbrella covers the remaining $1.5 million.
The Professional Liability Gap Umbrella Cannot Close
The most critical limitation studio owners must understand: a commercial umbrella almost never covers professional liability. Umbrella insurance raises limits for premises liability and general bodily injury claims, not instruction-related negligence.
If a client alleges improper cueing led to injury or that an instructor failed to modify an exercise appropriately, that claim falls under professional liability coverage. Umbrella will not increase those limits. Studios need separate professional liability policies with adequate limits, and instructors working as independent contractors must carry their own coverage.
When Pilates Studios Should Add Umbrella Coverage
Umbrella insurance costs $30 to $75 per month as an add-on to existing business owner's policies. The Hartford offers studios umbrella coverage for $2,500 to $4,000 annually, a modest upcharge when base Pilates studio insurance runs about $130 per month.
Not every studio needs umbrella coverage from day one, but specific growth milestones and operating characteristics create clear triggers for adding this layer of protection.
Multi-Location Operators
Expanding a boutique fitness studio doesn't automatically update coverage. If location, services, or staff details change and the policy doesn't reflect those changes, gaps form. Each additional location multiplies premises liability exposure, increasing the statistical likelihood of a claim that could exceed primary limits.
High-Volume Studios and Class Density
Studios running 30 or more classes per week with reformer sessions at or near capacity face higher cumulative exposure. More client hours on equipment means more opportunities for falls, collisions, and equipment-related injuries. High throughput also correlates with less individualized attention, which can contribute to injury risk.
Operations in High-Litigation States
California, New York, and Florida present higher jury awards and more plaintiff-friendly court environments. Average personal injury settlements exceed $2 million in major metropolitan areas in these states, making umbrella coverage particularly valuable for studios operating in Los Angeles, New York City, Miami, and San Francisco.
Studios Using Independent Contractor Instructors
General liability policies frequently exclude independent contractors altogether. Studios have two options: require each 1099 instructor to carry their own liability policy naming the studio as an additional insured, or extend contractor coverage through the facility's own policy. Either approach increases liability exposure and strengthens the case for umbrella coverage.
Coverage Gaps Most Studios Miss During Renewal
Gyms need more than basic general liability insurance; they need several types of coverage working together to close gaps a normal policy leaves open. Umbrella policies only function effectively when underlying coverage is properly structured.
Studios should verify that their general liability policy includes premises liability, products and completed operations coverage, and medical payments. They should confirm whether independent contractors are covered or excluded. They should understand the distinction between occurrence-based and claims-made professional liability policies and whether instructor coverage is included or requires separate endorsement.
Industry bodies like IHRSA have pointed out that liability claims can be particularly disruptive for independent fitness studios when coverage is limited or misunderstood. Even one claim can pull owners away from day-to-day operations and stall growth plans.
Real-World Claim Scenarios Where Umbrella Kicks In
Equipment and injury-related claims in cycling environments commonly involve tens of thousands of dollars in combined medical and legal costs, and Pilates involves similar high-end reformer equipment with moving parts and spring resistance.
Consider a client performing standing splits on the reformer carriage who loses balance, falls onto the frame, and suffers a compression fracture requiring surgery and months of rehabilitation. Medical costs exceed $150,000, the client cannot return to work for six months, and a lawsuit seeks $1.8 million in damages. The studio's $1 million general liability policy covers the first million; the umbrella policy covers the remaining $800,000 plus ongoing legal fees.
In another scenario, a pregnant client takes a pre-approved class, experiences a fall during footwork, and subsequently suffers pregnancy complications she attributes to the fall. The lawsuit names both instructor negligence and premises liability. Even if the studio prevails on the instruction claims, the premises component could produce a settlement or judgment exceeding primary limits.
What This Means for Studio Operators
Editorial analysis, not reported fact:
Umbrella insurance represents a relatively small investment that protects the personal assets studio owners have worked years to build. For single-location studios in low-litigation states with modest class volume, the immediate need may be limited. But for any studio crossing the threshold into multiple locations, operating at high volume, employing or contracting numerous instructors, or located in California, New York, or Florida, umbrella coverage should be part of the 2026 renewal conversation.
The decision point is not whether your studio has experienced claims in the past, but whether a single catastrophic injury could produce financial exposure exceeding $1 million. When your studio feels personal and community-led, it's easy to assume the risks are lower. In practice, smaller studios are often more vulnerable because they don't have the reserves to absorb legal fees, medical claims, or prolonged closures.
Bring umbrella coverage into your broker conversation at renewal. Ask for quotes at $1 million, $2 million, and $3 million excess limits. Confirm that your underlying general liability and professional liability policies are properly structured. Verify independent contractor coverage. And remember that umbrella does not replace professional liability coverage; it complements it by protecting against the premises and bodily injury claims that can exceed primary limits.
Sources & Further Reading
- The Hartford Commercial Umbrella Insurance, overview of umbrella coverage mechanics and pricing for small businesses
- Fullsteam Pilates Studios Insurance Guide, claims data and cost considerations specific to Pilates operations
- Smart Health Clubs Insurance for Boutique Fitness Studios, risk perception and coverage gaps for independent studios
- Nexofit Complete Gym Insurance Guide, comprehensive breakdown of coverage types for fitness facilities
- Morrow Insurance Professional Liability for Pilates Instructors, explanation of professional liability limits and umbrella exclusions
- Nexofit Insurance Review When Expanding, coverage considerations for multi-location growth
Editorial coverage of publicly reported industry developments. The Pilates Business has no commercial relationship with any companies named.